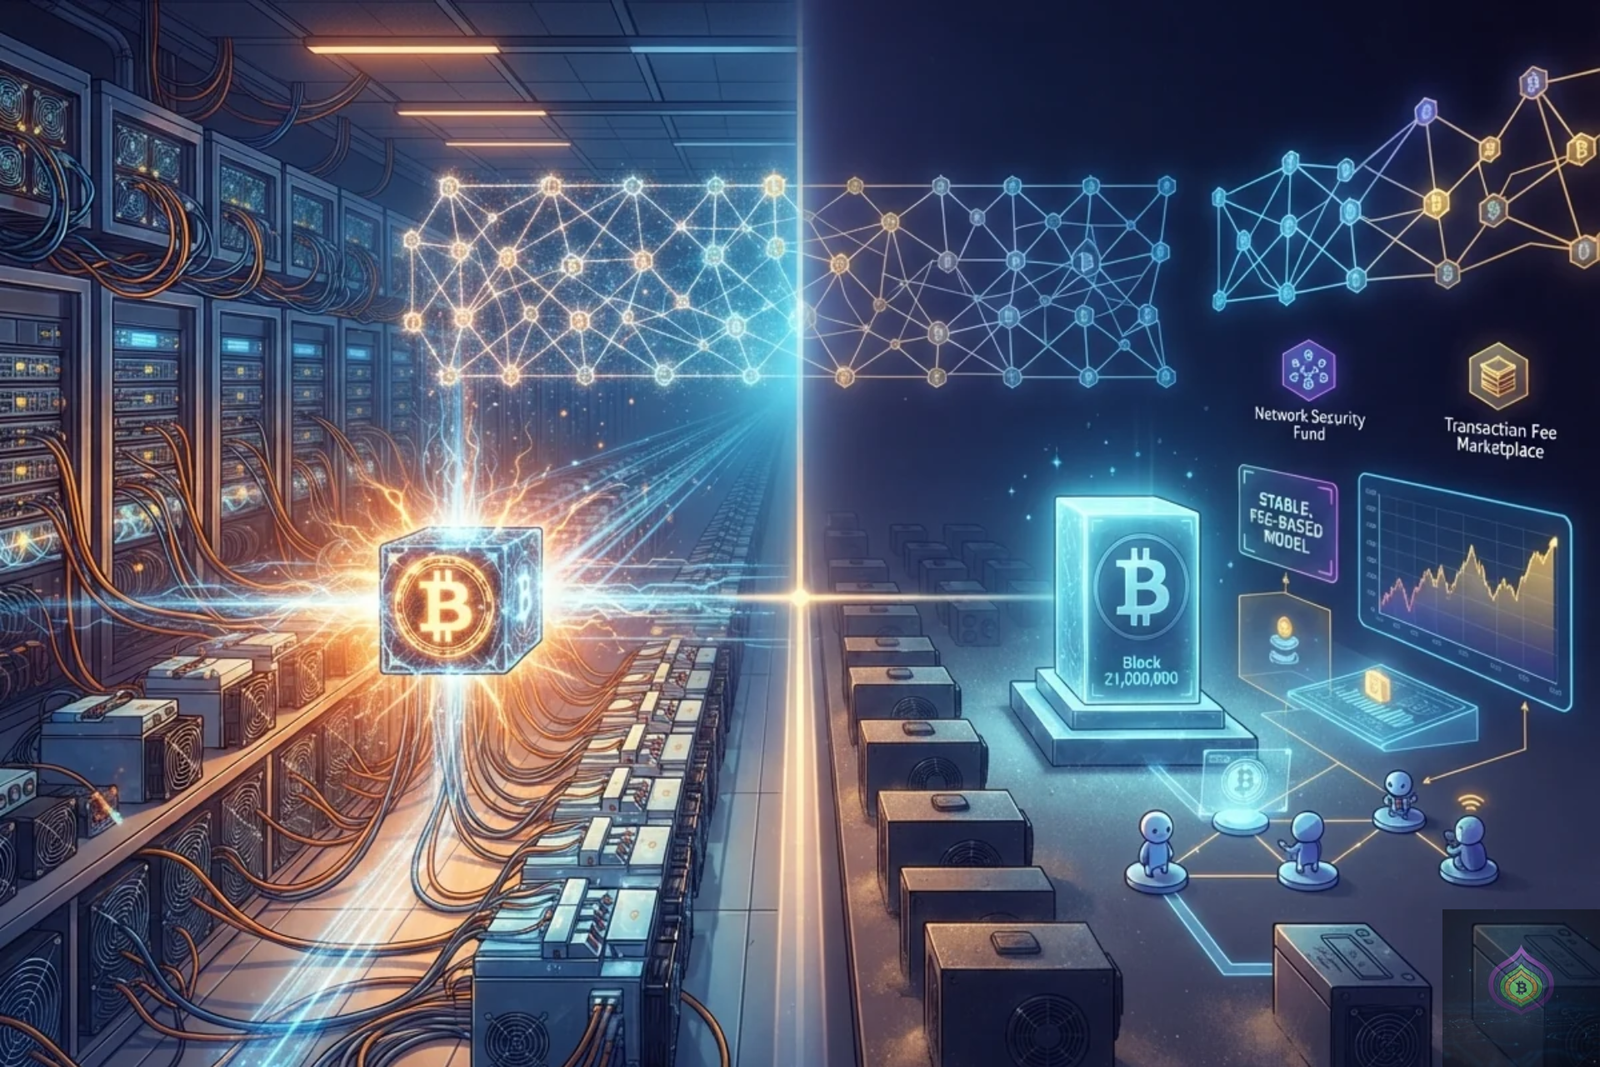
Bitcoin has a built-in expiry date for new coin creation: approximately 2140. What happens to miners, security, and Bitcoin’s value when the last block reward reaches zero is one of the most important — and most misunderstood — questions in cryptocurrency
Most people know that Bitcoin has a finite supply of 21 million coins. Fewer understand the mechanism that creates and enforces this limit — and even fewer have thought carefully about what happens when that mechanism winds down. Satoshi Nakamoto designed Bitcoin with a deliberate, mathematically precise answer to ‘what happens when the reward runs out.’ Whether that answer is adequate is one of the most debated questions among Bitcoin researchers and economists.
This guide covers the technical reality of how Bitcoin mining ends, what the transition from block reward to fee-only security means for miners, users, and Bitcoin’s security, and the honest arguments on both sides of the ‘Bitcoin security budget’ debate.
First: How Bitcoin Mining Currently Works
Bitcoin’s blockchain is secured by proof of work — a mechanism where miners compete to solve a computationally expensive mathematical puzzle. The first miner to solve it adds the next block to the blockchain and receives a reward. This reward has two components:
- Block subsidy: Newly created Bitcoin awarded to the miner for adding a valid block — currently 3.125 BTC per block after the April 2024 halving
- Transaction fees: The sum of all fees paid by users whose transactions are included in that block
The block subsidy is what creates new Bitcoin and drives the exponential miner revenue that has historically made mining profitable at scale. The transaction fees are what remains after the subsidy disappears. Understanding the transition between these two revenue sources is the core of understanding what happens when Bitcoin mining ends — or more precisely, when new Bitcoin creation ends.
📌 The Critical Distinction: Bitcoin mining doesn’t ‘stop’ in the sense that no new blocks will be produced. Mining — the process of adding new transactions to the blockchain and securing the network — continues indefinitely. What stops is the creation of new Bitcoin. After the final block reward reaches zero (approximately 2140), miners continue to exist and operate, but they earn only from transaction fees. This distinction is important for understanding what ‘Bitcoin mining stops’ actually means.
The Halving Schedule — The Road to Zero
Bitcoin’s block subsidy halves approximately every four years — specifically, every 210,000 blocks. This was designed by Satoshi to create a predictable, transparent, and tamper-proof monetary issuance schedule. The halvings follow a precise mathematical sequence:
- 2009 (Genesis): 50 BTC per block — the original reward that bootstrapped the entire network
- 2012 (1st halving): 25 BTC per block
- 2016 (2nd halving): 12.5 BTC per block
- 2020 (3rd halving): 6.25 BTC per block
- 2024 (4th halving, April): 3.125 BTC per block — the current reward
- 2028 (5th projected): 1.5625 BTC per block
- 2032 (6th projected): 0.78125 BTC per block
- …continuing 29 more halvings until the reward rounds to 0 satoshis (1 sat = 0.00000001 BTC)
By approximately 2140 — roughly 114 years from now — the 32nd or 33rd halving will reduce the block reward to below 1 satoshi, at which point no new Bitcoin can be created and the subsidy effectively reaches zero. The final 21 millionth Bitcoin won’t actually be a clean round number event — it approaches asymptotically as rewards get fractionally smaller with each halving.
🔢 The Mathematics of Bitcoin’s Supply Cap: Bitcoin’s total supply is the geometric series sum of all block rewards across all halvings: 50 + 25 + 12.5 + … = 21 million (approximately). The cap is enforced by the protocol itself — no majority of miners, users, or developers can increase the supply without a fundamental change to Bitcoin’s core rules that would create a different currency. This mathematical certainty is central to Bitcoin’s ‘digital gold’ value proposition.
What Happens Immediately When the Last Block Reward Reaches Zero
The transition won’t be a single dramatic event — it will be the final step in a 130-year gradual process. By 2140, the block subsidy will have been declining for over a century. Miners will have been operating in a fee-only environment long before the final subsidy disappears. Here’s what actually changes:
For Miners: The Revenue Model Transforms Completely
Currently, block subsidies account for the vast majority of miner revenue — transaction fees typically represent 5–15% of total miner income in normal market conditions (though they spiked to 40%+ during the 2023 Ordinals/Inscriptions surge, demonstrating that fee-based revenue can be significant). In 2140, fees become 100% of miner revenue. The economic viability of mining then depends entirely on:
- Bitcoin’s price per coin — if each bitcoin is worth $1 million (in today’s terms), even small fee percentages represent substantial dollar revenue
- Transaction volume — higher network usage generates more total fees for miners to compete for
- Fee per transaction — if Bitcoin is used primarily for large-value settlements, fees per transaction can be high
- Mining efficiency — technological progress will have continued for 114 more years, making hardware far more efficient
For Users: Transaction Experience May Change
In a fee-only mining environment, miners only include transactions that pay sufficient fees to make block inclusion profitable. In today’s market, low-fee transactions often still confirm within hours or days. In a fee-only environment, the minimum economically rational fee level rises — miners have no subsidy revenue to subsidise transaction processing for low-fee users. This has implications for Bitcoin’s use as an everyday payment layer versus its use as a high-value settlement layer.
For Bitcoin’s Price: Deflationary Dynamics Intensify
Every halving reduces new Bitcoin supply entering the market. After the final halving, new supply is zero — while demand (if maintained or growing) continues. All else equal, zero new supply with positive demand implies persistent upward price pressure. This is why many Bitcoin analysts model an indefinitely appreciating price in the long run, though actual price depends on countless factors beyond supply alone.
The Security Budget Problem — The Most Important Open Question
This is where Bitcoin’s future gets genuinely contested among serious researchers. The security budget problem asks: will transaction fees alone provide sufficient economic incentive for miners to secure the network?
Why Miner Revenue Matters for Security
Bitcoin’s security model works because attacking the network — rewriting transaction history through a 51% attack — costs more than it’s worth. This is true when mining is profitable: a rational attacker who can afford to rent or buy 51% of the hashrate would find it more profitable to mine honestly than to attack the network. If mining becomes unprofitable, hashrate drops, security declines, and attacks become cheaper.
The block subsidy currently provides the bulk of miner revenue, keeping mining profitable even when transaction fees are low. As the subsidy declines through successive halvings, the question is: will transaction fees grow to fill the gap?
The Optimistic Case — Fees Will Grow
Bitcoin optimists argue that fees will naturally grow to maintain security because:
- Bitcoin’s price has historically increased dramatically between halvings — if Bitcoin is worth 10x more per coin at the next halving, miners can be equally profitable with half the subsidy
- Layer 2 solutions like Lightning Network can dramatically increase Bitcoin’s transaction throughput — and fee revenue to miners — by settling large volumes of off-chain transactions on-chain
- Bitcoin’s potential role as a global settlement layer means individual transactions will be very high value — and users will rationally pay significant fees for the security of settlement on the most secure blockchain
- Ordinals and Inscriptions demonstrated in 2023 that new use cases can dramatically increase fee revenue — generating $100M+ in fees and showing that the fee market is more dynamic than previously assumed
- By 2140, Bitcoin’s technology ecosystem will have evolved in ways we can’t predict — potentially including fee mechanisms we don’t currently anticipate
The Pessimistic Case — Fee Revenue May Be Insufficient
Bitcoin researchers including Giacomo Zucco, Paul Sztorc, and others have raised concerns:
- Transaction fees have historically been volatile and insufficient — even at Bitcoin’s $1 trillion+ market cap, fee revenue alone has represented only a fraction of what would be needed to maintain current hashrate
- Competition from other blockchains for transaction fee revenue may fragment the market, keeping individual chain fees low
- If Bitcoin succeeds as a settlement layer for Lightning Network, the on-chain transactions themselves may be infrequent — each settling many smaller Lightning payments — potentially limiting fee volume
- The security threshold isn’t binary — the question is whether the ratio of mining cost to attack cost remains adequate over decades
💡 The Timescale Reality: This debate, while substantively important, has a crucial context: we’re discussing events that will unfold over 114 years. Bitcoin has existed for 15 years. Making specific predictions about 2140’s fee market, Bitcoin’s price, technological alternatives, and geopolitical context requires extraordinary confidence about the future. The security budget question is real and worth ongoing research — but solving it urgently in 2026 is not necessary for Bitcoin’s continued utility today.
What Happens to Miners After the Last Block Reward
Predicting 2140’s mining industry is inherently speculative, but the economic logic suggests several outcomes:
Mining Consolidation
As subsidies decline through successive halvings, less efficient miners exit the market. This consolidation has been visible in every halving cycle — after the April 2024 halving, smaller miners with higher operational costs faced significant pressure. By 2140, surviving miners will likely be large, highly efficient operations with access to the cheapest available electricity. The mining industry will look more like an oligopoly of industrial-scale operations than today’s more distributed landscape.
Geographic Concentration Around Energy
In a fee-only environment with no block subsidy, energy cost becomes the dominant variable for profitability. Mining will concentrate further in regions with the cheapest electricity — stranded hydro, excess renewable, or other energy sources that can’t be transported elsewhere. The geographic distribution of mining will reflect global energy economics rather than regulatory incentives.
Potential Protocol Evolution
Bitcoin’s protocol has evolved slowly and deliberately over 15 years — but 114 years is a very long time. The Bitcoin development community could theoretically implement protocol changes that address the security budget concern before it becomes acute. Proposed solutions include: tail emission (a small permanent subsidy), demurrage fees, or alternative security mechanisms. Whether such changes would be adopted is unknown — Bitcoin’s governance process moves slowly and conservatively by design — but ruling them out completely ignores the reality of Bitcoin’s adaptive development.
🧠 The Time Perspective: The most important thing to understand about ‘what happens when Bitcoin mining stops’ is the timeline. The subsidy doesn’t stop tomorrow — it continues declining gradually for over a century. Each halving provides years for the ecosystem to adapt. The final transition to fee-only mining will be the last step of a long-observed and studied process, not a sudden cliff. Bitcoin in 2140 will be shaped by 115 years of technological evolution, regulatory development, and market forces we genuinely cannot predict from 2026.
What Doesn’t Change When Mining Rewards End
Understanding what doesn’t change is as important as what does:
- The 21 million supply cap remains absolute: No mining ending changes the cap — it’s enforced by the protocol, not by mining
- Bitcoin transactions continue: The blockchain continues to produce blocks, process transactions, and settle value — mining doesn’t stop, just the new coin creation
- Existing Bitcoin remains valid: Every Bitcoin mined before the final block remains a valid, transferable asset indefinitely
- The security model continues in principle: Transaction fees continue to incentivise mining — whether they incentivise enough mining is the contested question
- Decentralisation principles remain: Bitcoin’s consensus mechanism, node validation, and governance processes are unchanged by the end of block subsidies
⛏️ The Last Block Is 114 Years Away — Understand It Anyway
Bitcoin mining’s transition from subsidy-driven to fee-driven security is one of the most important long-term questions in cryptocurrency. The security budget debate is genuine and ongoing — but the timeline gives Bitcoin’s ecosystem over a century to adapt, innovate, and address the challenge through technological and market evolution. The 2140 endpoint isn’t a crisis approaching — it’s a long-anticipated feature of Bitcoin’s design that has been understood since the Bitcoin whitepaper.
For today’s Bitcoin holders and investors: the halving dynamics that reduce new supply every four years are the near-term expression of the same mechanism. Each halving’s impact on miner economics and Bitcoin’s price are the proving grounds for the fee-based security model long before 2140 arrives.
✅ Track Bitcoin’s current block subsidy and fee dynamics at mempool.space — live data on miner revenue composition.
✅ Study the halving schedule and its historical market impact — each halving is a data point in the long-term security budget question.
✅ Follow the security budget debate through Bitcoin research at bitcoin.org/en/bitcoin-paper and academic papers from the Scaling Bitcoin conference.
👉 Share this guide with any Bitcoin holder who wonders about 2140 — because understanding Bitcoin’s design is part of understanding Bitcoin’s value.
Frequently Asked Questions (FAQs)
1. When exactly will Bitcoin mining stop creating new coins?
The last Bitcoin will be mined (as a practical matter) around the year 2140 — approximately 114 years from now. More precisely, Bitcoin’s halving schedule divides the block reward by two every 210,000 blocks (roughly four years). After approximately 32–33 halvings, the reward will drop below 1 satoshi (the smallest Bitcoin unit, 0.00000001 BTC) and effectively round to zero. The exact date depends on average block times, which fluctuate around the 10-minute target. The final Bitcoin won’t be mined in a single dramatic block — the supply approaches its 21 million limit asymptotically, with the last few hundred thousand Bitcoin taking many decades to be mined due to exponentially decreasing block rewards.
2. Will Bitcoin become worthless when mining stops?
No — and this concern reflects a common misunderstanding. Bitcoin’s value comes from its usefulness as a store of value, medium of exchange, and settlement layer — not from the process of creating new Bitcoin. Gold doesn’t become worthless because no new gold is being mined in a particular period; the existing stock retains value based on demand. Bitcoin’s 21 million supply cap arguably increases its value proposition as a store of value — it’s the predictable scarcity that makes it attractive. When the last block subsidy reaches zero, the 21 million existing Bitcoins continue as transferable, valid assets. What changes is the economic incentive structure for miners — which shifts entirely to transaction fees. Whether those fees are sufficient for network security is the genuinely contested question.
3. What is the ‘security budget problem’ in Bitcoin?
The security budget problem refers to the concern that, as Bitcoin’s block subsidies decline through successive halvings, transaction fees alone may not provide sufficient revenue to keep enough miners operating to secure the network against 51% attacks. Currently, block subsidies represent approximately 85–95% of miner revenue in normal fee conditions. As this proportion declines, the question is whether transaction fee revenue will grow proportionally. The optimistic case argues that Bitcoin’s price appreciation and increasing transaction volume will naturally grow fee revenue to maintain security. The pessimistic case argues that historical fee levels have been too low and volatile to rely on. This debate is ongoing and unresolved — it’s among the most important long-term research questions in Bitcoin.
4. Can Bitcoin’s protocol be changed to add more supply?
Technically, Bitcoin’s protocol can be modified by any network participant — the code is open source. However, actually implementing a supply increase would require broad consensus from the network’s miners, developers, exchanges, and users — and any such change would effectively create a different cryptocurrency, not Bitcoin. The 21 million supply cap is Bitcoin’s most sacred property: it’s been present since Satoshi’s original whitepaper, and any change to it would represent such a fundamental departure from Bitcoin’s design that it would almost certainly result in a network split. Users and exchanges would face a choice between the original cap-enforcing chain and the new chain — historically in such disputes, the original chain (the one with more economic support) tends to be recognised as ‘Bitcoin.’ The cap is enforced by the distributed network, not by any central authority — no company, government, or developer can unilaterally change it.
5. What happens to the Bitcoin I already own after mining stops?
Nothing changes for existing Bitcoin holders when mining stops creating new coins. Your Bitcoin:
(1) Remains valid and transferable: Every Bitcoin mined before the final block is a permanent, valid entry in the blockchain — it can be sent and received indefinitely;
(2) Gains enhanced scarcity: With zero new supply entering the market, existing Bitcoin becomes more scarce in absolute terms — which all else equal is positive for holders if demand persists;
(3) Can still be transacted: The blockchain continues producing blocks and processing transactions — Bitcoin can still be used for payments, stored in wallets, and traded on exchanges;
(4) Maintains all security properties: As long as sufficient hashrate exists (the security budget question), transactions remain irreversible and the blockchain remains tamper-evident.
The halting of new coin creation changes nothing about your existing Bitcoin’s validity — it only changes the dynamics of miner revenue and network security.